Buying a first home in Coogee is rarely decided at the inspection. It is decided weeks earlier, when you work out what you can borrow, what you can comfortably repay, and which streets and property types genuinely fit your budget.
Preparation matters when buying a first home in Coogee. Working out your borrowing position, comfortable repayment level and property priorities before inspecting can help you make decisions without relying on assumptions or emotion.
This guide walks through that preparation in order: borrowing capacity, pre-approval, documents, a realistic search strategy, and how to compete at inspections and auctions without stretching yourself past the point of comfort. Our Coogee mortgage broker page covers the suburb-specific lending side of that conversation if you would rather start there.
Buying a First Home in Coogee: Why Preparation Matters
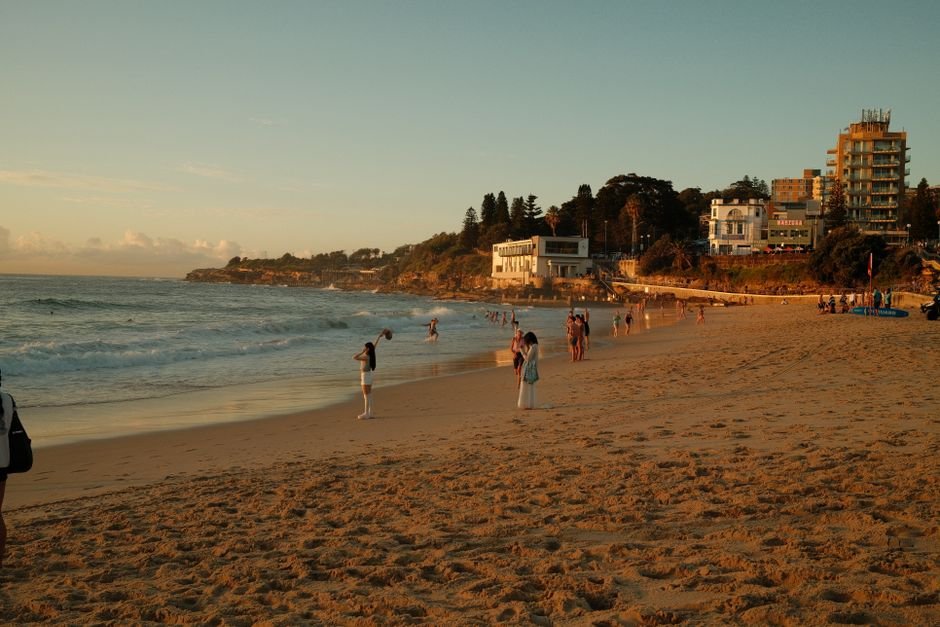
Coogee offers beach access, local shops, public transport connections and proximity to other Eastern Suburbs centres. Those features can make it attractive to a wide range of buyers, so a first-home buyer should approach the search with a clear budget and defined property priorities.
Your suitable property type will depend on your borrowing position, deposit, ongoing costs and plans for the next several years. Rather than assuming a particular property type will be within reach, compare recent sales and assess each property against your approved budget and repayment comfort.
Sort Out Your Borrowing Limit Before You Inspect
A borrowing limit is not the same as a budget. Lenders assess how much they are willing to lend based on income, existing debts, living expenses and the deposit you can demonstrate. Your own budget should sit below that number once you factor in repayments at a higher rate than the one you are quoted, plus council rates, strata levies where relevant, insurance and maintenance.
Working out this number early changes how you search. Instead of browsing listings and hoping, you filter by what you can actually service. This means fewer wasted Saturdays and less emotional attachment to properties that were never within reach.
What Pre-approval Does and Does Not Do
Pre-approval is a lender’s indication that your situation fits its lending criteria, subject to conditions. It can give you confidence to make an offer and indicate to agents that you are a genuine buyer.
It is not a guarantee of approval, and it does not lock in a property. A valuation, a change in your circumstances or a property the lender considers unsuitable can affect the final outcome. Treat pre-approval as a strong starting position, not a finish line.
Documents to Gather Early
Collecting paperwork ahead of time can shorten the application process. Most applications require a similar core set of documents:
- Photo identification and proof of address
- Recent payslips and an employment letter or contract
- Bank statements showing savings history and day-to-day spending
- Credit card and personal loan statements, plus details of other debts
- Evidence of genuine savings or gifted funds where applicable
- For self-employed buyers, recent tax returns and notices of assessment
If a document is missing or unclear, the lender may ask for more information, and each round trip can add time. A broker can review the file before submission so gaps are found early rather than during a cooling-off period.
Build a Realistic Search Strategy for Coogee
Set a firm ceiling before you start inspecting and write it down. Then decide which features you will not compromise on and which ones you are prepared to trade.
A north-facing balcony, car space and short walk to the beach may all be desirable, but very few first purchases deliver every item on the list. Knowing your order of priority can stop a suitable property from feeling like an unnecessary compromise.
Track sold results as closely as you track listings. Looking at what comparable properties actually sold for, rather than relying only on advertised prices, can give you a clearer picture of how different properties and locations compare. CBM Mortgages can also provide property reports containing comparable sales and available local market information to support your research.
Which Property Types May Suit a First Purchase?
A first purchase in Coogee may involve an apartment, townhouse or house, depending on your budget and requirements. Compare the purchase price with ongoing expenses, maintenance responsibilities and how well the property is likely to suit your plans over the next several years.
Strata is a separate topic, with levies, by-laws, building reports and lender treatment all requiring attention. Our guide to buying an apartment in Coogee explains these checks in more detail. If you are considering a unit, read that guide before you exchange contracts.
Widen the Search Without Losing Sight of Your Priorities
If suitable properties in Coogee fall outside your budget or requirements, consider widening the search to nearby Eastern Suburbs locations. Comparing several suburbs can increase the number of properties available while allowing you to weigh travel, lifestyle, property type and ongoing costs against your priorities.
Competing at Inspections and Auctions Without Overextending
Once you are pre-approved and your ceiling is set, competing becomes a matter of discipline. At inspections, ask about building defects, recent repairs, strata minutes and why the owner is selling.
Ask your solicitor or conveyancer which building, pest, strata and contract checks are appropriate for the property before you make an unconditional commitment.
Auction and private-treaty sales follow different rules. Your solicitor or conveyancer should explain what applies to the contract you are considering before you bid or sign.
At auction, decide your maximum before the day, write it down and stop when the bidding reaches that figure. A property you lose is recoverable. A loan you cannot comfortably repay is not.
Where a Broker Helps in the Coogee Market
First-home buyers often assume the only variable is the interest rate. In practice, the loan structure, deposit, income, liabilities, property type and any government assistance for which you may be eligible can all affect the outcome.
First-home-buyer support programs have eligibility rules that can change. Check current information with Housing Australia and Revenue NSW, or ask your broker to explain which current options may be relevant to your circumstances.
Our First Home Buyers service is built around that process: reviewing your position, comparing suitable options from our lender panel, preparing your documents and providing plain-English guidance through to settlement.
CBM Mortgages cannot promise approval because the final decision sits with the lender. However, a well-prepared application can help you understand the available options and trade-offs before committing to a property.
If you are also considering what the purchase will cost beyond the property price, our guide to the upfront costs of buying your first home in Sydney covers deposits, purchase costs and other expenses in more detail.
Get the finance and search strategy right, and Coogee can become a location where you know exactly what you are looking for and what you can comfortably afford.
Frequently Asked Questions
How much deposit do I need to buy a first home in Coogee?
There is no single answer because deposit requirements depend on the lender, loan product and your overall financial position. Some buyers use a smaller deposit, while others save a larger one to reduce the amount borrowed.
Government schemes may assist eligible buyers, and current eligibility rules should be checked with Housing Australia and Revenue NSW. A broker can explain how different deposit levels may affect your options.
Can I get pre-approval before I start inspecting properties?
Yes, and it is usually the better order of events. Pre-approval gives you an assessed borrowing range so you can inspect properties within your means rather than guessing.
Remember that pre-approval is conditional rather than a guarantee. The lender will still assess the specific property and your circumstances before final approval.
Should I buy an apartment or a house as a first home in Coogee?
The right property type depends on your budget, borrowing position, ongoing costs and plans for the next several years.
If you are considering an apartment or townhouse, review the strata records, levies, by-laws and building condition before committing. Our dedicated Coogee apartment guide explains those checks in more detail.
How long does the pre-approval and application process take?
Timelines vary depending on the lender and how quickly you can supply the required documents. Files that are complete at submission generally move more efficiently than applications requiring repeated follow-up.
Gathering payslips, statements and identification early, and having a broker review the file before submission, can help reduce avoidable delays.
How do I avoid overpaying when the market feels competitive?
Set your maximum before you inspect and treat it as fixed. Attend auctions without bidding to learn how they operate, track sold prices rather than relying only on asking prices, and obtain the appropriate contract, building, pest and strata checks before committing.
Losing a property because another buyer exceeded your comfortable limit is a normal part of the process. Extending your repayments beyond a sustainable level can create a much longer-term problem.
Planning to Buy Your First Home in Coogee?
CBM Mortgages can help you understand your borrowing position, compare suitable options from our lender panel and prepare your home loan application from enquiry through to settlement.
Disclaimer: This article provides general information only and does not constitute personal financial, legal, tax or credit advice. Lending criteria, government programs, interest rates, fees and lender policies can change. Any loan application is subject to lender assessment and approval. Consider your circumstances and obtain appropriate professional advice before making a financial decision.
Written by Craig McDonald. Updated November 2026.